Illicit finance quarterly

A unified front for European financial integrity
The EU’s creation of the Anti-Money Laundering Authority marks a substantial shift towards centralized supervision.
Targeting professional enablers in the UK
The UK has tightened its financial crime framework, expanding corporate liability and increasing scrutiny of professions that facilitate illicit finance.
Iran’s shadow fleet in a period of escalating conflict
The architecture of sanctions evasion – Iran’s oil transport network has evolved into a sophisticated sanctions‑evasion system. Heightened geopolitical tension is complicating its activity.
Fuel trade capture in the Central African Republic
The state’s supply chains have been captured by politically connected intermediaries, introducing risk into regional banking, trade finance and cross‑border payment systems.
MARKET TYPOLOGY
The Canadian fentanyl economy
The financial patterns of this domestic illicit economy mirror the broader global shift towards highly adaptable synthetic‑drug supply chains.
SECTION #1
Navigating financial crime risk
A unified front for European financial integrity
The EU is restructuring its anti-money laundering framework with the creation of the Anti-Money Laundering Authority (AMLA) and a new single rulebook for anti-money laundering and combating the financing of terrorism (AML/CFT) supervision. The reform aims to strengthen coordination and enforcement across EU financial institutions after years of fragmented national supervision. Stricter EU oversight and enhanced due-diligence expectations could affect correspondent banking relationships and cross-border compliance requirements involving jurisdictions on the EU high-risk lists.
The launch of the European Anti-Money Laundering Authority (AMLA) in Frankfurt in July 2025 marked a structural change in the EU’s AML architecture. Established under Regulation (EU) 2024/1620 as part of the EU’s 2024 AML/CFT legislative package, the AMLA is designed to centralize supervisory coordination and, in limited cases, directly supervise high-risk cross-border institutions.
For years, AML enforcement in the EU was governed by directives, most recently the 5th and 6th AML directives, which required national transposition. This produced uneven supervisory practice across Member States, a vulnerability repeatedly exposed in cross-border banking scandals. The shift toward a directly applicable AML regulation, the Single Rulebook, represents a move away from fragmented implementation towards uniform legal standards across the bloc.
However, the key policy question is not simply whether there will be more rules, but whether harmonization will raise standards to the highest existing benchmark or converge toward a political compromise. In theory, the new AML Regulation (EU) 2024/1624 sets directly applicable requirements on customer due diligence, beneficial ownership and reporting obligations. In practice, the level of supervisory intensity will depend on how the AMLA exercises its coordination powers and how national authorities implement technical standards. Harmonization does not automatically mean upward convergence.
A major milestone will occur in 2027, when the AMLA is expected to select up to 40 of the highest risk and most cross-border institutions for direct supervision beginning in 2028. These institutions will be chosen based on cross-border activity and risk profile. Although the AMLA has not indicated which institutions may fall within the initial cohort, several large EU banking groups maintain extensive subsidiary and correspondent networks across Africa. If institutions with significant exposure to these markets are selected for direct supervision, the AMLA’s supervisory posture could indirectly influence EU–Africa financial corridors, particularly in areas such as enhanced due diligence requirements and correspondent banking relationships.
From the standpoint of EU–Africa financial relations, the relevance lies less in direct AMLA supervision and more in EU external risk policy. The European Commission’s high-risk third-country jurisdictions list, aligned but not identical to that of the Financial Action Task Force (FATF), has expanded in recent years to include several African states, including Angola, Namibia and Kenya. Several countries across the continent have also been grey listed by the FATF, affecting correspondent banking relationships and trade finance flows. If the AMLA drives stricter enforcement of enhanced due diligence requirements for listed jurisdictions, EU banks may reassess risk exposure in parts of Africa, with potential implications for cross-border financial connectivity.
National supervisors such as the Federal Financial Supervisory Authority (BaFin) in Germany will retain day-to-day oversight of most institutions, but under strengthened EU-level coordination. The AMLA will also have powers to mediate disputes between national authorities and to issue binding decisions in specific circumstances.
Ultimately, the AMLA’s success will depend less on its formal establishment and more on its ability to enforce supervisory convergence in politically sensitive cases. The EU now has a central authority; whether it becomes a strong prudential-style supervisor or remains primarily a coordination body will determine whether this reform meaningfully reshapes financial integrity across the bloc.
Targeting professional enablers in the UK
The UK is tightening its economic crime framework with new corporate liability rules and increased scrutiny of professional enablers such as lawyers, accountants and corporate service providers. The reforms aim to strengthen enforcement against the professional infrastructure that facilitates illicit financial flows. The changes are particularly relevant in cases where corruption and asset-concealment schemes linked to politically exposed persons rely on international professional service networks operating through the UK.
The UK has announced an ambitious recalibration of its financial crime framework, shifting its focus towards professional enablers, lawyers, accountants and financial intermediaries who facilitate illicit finance. This emphasis appears across recent policy initiatives, including the UK’s Economic Crime Plan 2 (2023–2026) and the government’s Anti-Corruption Strategy 2025, both of which highlight the role of professional infrastructure in enabling illicit finance. The development reflects growing concern about the scale of illicit finance moving through the UK, which the National Crime Agency estimates may exceed £100 billion annually.
The UK’s Economic Crime Plan 2 and subsequent enforcement reforms, alongside the Economic Crime and Corporate Transparency Act 2023 (ECCTA), introduce significant new corporate liability mechanisms. Chief among these is the ‘failure to prevent fraud’ offence, introduced under the ECCTA, which came into force on 1 September 2025. This provision allows for corporate criminal liability if an associated person commits fraud for the company’s benefit, unless the company can demonstrate it had reasonable prevention procedures in place.
Legislatively, this is robust. It builds on earlier failure-to-prevent models, such as that under the UK’s Bribery Act 2010 – widely regarded as one of the world’s strongest anti-corruption laws. The more difficult question is enforcement capacity.
The UK has a history of strong statutory frameworks coupled with uneven enforcement outcomes. A prominent example is the Criminal Finances Act 2017, which introduced unexplained wealth orders (UWOs) as a tool to target suspiciously acquired assets. In 2020, the National Crime Agency pursued high-profile UWO proceedings involving three London properties worth approximately £80 million, which were linked to Dariga Nazarbayeva, a daughter of former Kazakh President Nursultan Nazarbayev, and her son Nurali Aliyev. The court ultimately discharged the orders and the agency faced substantial legal costs. The outcome highlighted the asymmetry between well-resourced private defendants and publicly funded enforcement bodies, raising concerns about whether such tools can be deployed consistently against sophisticated actors.
This history matters. Expansive legal tools are only as effective as the institutions tasked with enforcing them. The ECCTA enhances verification requirements at Companies House, the UK’s corporate registry, alongside broader corporate transparency mechanisms; however, enforcement will depend on sustained funding, effective investigative coordination and a prosecutorial appetite.
Similarly, while the Financial Conduct Authority, the UK’s financial regulator, plays a central supervisory role in AML oversight of regulated financial institutions, many lawyers and accountants are still supervised by professional body regulators. Although multilayered supervision is common internationally, the UK’s unusually large number of professional body supervisors has long drawn criticism for creating fragmentation and inconsistent enforcement standards.
There is also the question of extra-territorial ambition. UK authorities frequently emphasize their intent to pursue misconduct involving a ‘UK nexus’, including foreign professionals using London-based financial structures. Yet cross-border asset recovery and prosecution remain resource-intensive and diplomatically complex.
The relevance of these reforms also extends to the international professional service networks through which illicit financial flows connected to African corruption cases have historically been structured. A 2023 Transparency International study analyzing 78 cases of high-level corruption across 33 African countries identified 87 professional enablers, including lawyers, accountants, corporate service providers and real estate agents, who assisted African politically exposed persons in concealing and transferring illicit wealth abroad. While the report focuses on non-financial professional facilitators, it highlights how such actors can assist politically exposed persons in structuring corporate arrangements, legal documentation and asset holdings in ways that obscure beneficial ownership and allow funds to move through the international financial system with reduced scrutiny.
Notably, the report found that UK-based enablers were more strongly linked to Nigerian corruption cases than those from any other foreign jurisdiction. As UK authorities increase scrutiny of professional facilitators and strengthen corporate transparency, enforcement actions targeting these intermediaries could affect the international service infrastructure through which corruption proceeds connected to African jurisdictions have historically moved.
The UK’s legislative direction is clear: shift liability towards institutional prevention and make governance systems legally consequential. Whether this produces a genuine deterrent effect will depend on three key variables: sustained funding for enforcement agencies, political willingness to pursue complex transnational cases, and a judicial appetite to uphold aggressive interpretations of corporate liability.
The UK has demonstrated that it can draft world-leading legislation. The test, as past UWO litigation illustrates, is whether enforcement agencies are resourced and politically supported to apply these tools consistently against sophisticated and well-funded actors.
Iran’s shadow fleet in a period of escalating conflict: The architecture of sanctions evasion
Escalating tensions between Iran, Israel and the US are increasing pressure on Iran to sustain oil revenues through its shadow fleet, a network of vessels that moves sanctioned crude through commercial structures that closely resemble legitimate trade. As enforcement pressure grows, these structures become more layered and harder to penetrate, increasing the probability that transactions connected to sanctioned entities will surface in trade finance, commodity trading and correspondent banking flows. African maritime registries are embedded in this infrastructure, while the region's expanding role in commodity trade creates direct points of intersection with these networks.
Escalating tensions between Iran, Israel and the US have increased uncertainty in the Persian Gulf and surrounding maritime routes. Periods of geopolitical confrontation historically place additional pressure on sanctioned economies to maintain export revenues through alternative channels. For Iran, this has reinforced reliance on a large network of vessels commonly referred to as the shadow fleet, used to sustain oil exports despite extensive sanctions.
The shadow fleet has become a central mechanism through which Iranian crude continues to enter international markets. These vessels operate through a combination of deceptive shipping practices, opaque ownership structures, and fragmented financial arrangements designed to obscure the origin of cargo and the beneficiaries of trade. As these structures become more sophisticated, the probability increases that sanctioned commodities become integrated into legitimate global supply chains and into the transaction flows that pass through the financial system.
A mature system of sanctions evasion
Iran’s shadow fleet has developed over more than a decade of sustained sanctions pressure. Hundreds of tankers are estimated to participate in the transport of Iranian oil, typically operating under falsified or frequently rotating flag registrations. The operational sophistication of these arrangements reflects years of adaptation to enforcement pressure.
A widely documented tactic is the manipulation of automatic identification system (AIS) signals. Although AIS transponders exist to broadcast vessel location for maritime safety, vessels engaged in sanctions-evasion trade frequently disable or obscure these signals to conceal movements. This often coincides with ship-to-ship transfers in international waters, where sanctioned crude is blended with other supplies before being transported onward, in effect laundering the cargo’s origin through a maritime transaction.
Documentation practices reinforce this concealment. Oil originating in Iran may be accompanied by misleading or falsified certificates of origin, allowing it to enter global markets as crude sourced from other jurisdictions. Vessels involved in these trades also frequently reflag through maritime registries with limited oversight, including registries in Cameroon, Comoros, São Tomé and Príncipe, and Tanzania. While flags of convenience are common in global shipping and not inherently unlawful, frequent reflagging through registries with minimal monitoring creates additional challenges for those seeking to verify vessel ownership and operational history.
Many shadow fleet vessels operate outside the International Group of P&I Clubs, the body that provides most global maritime liability insurance and applies strict compliance standards. Instead, these vessels rely on insurers with limited transparency or financial capacity. The absence of reputable maritime insurance is a recognized indicator of potential sanctions exposure.
How escalating tensions may affect shadow fleet activity
Periods of heightened geopolitical tension tend to reinforce the incentives driving sanctioned oil exports through less transparent maritime channels. Increased regulatory scrutiny and the prospect of additional enforcement typically prompt operators to adopt more complex routing patterns, rely more heavily on intermediary trading companies, and introduce additional layers of corporate ownership, precisely the features that make underlying transactions harder to assess.
Shadow fleet activity may therefore become more fragmented and geographically dispersed as ships are forced to take alternative routes, such as the Cape of Good Hope and the Mozambique Channel. Offshore ship-to-ship transfers are likely to increase, intermediary jurisdictions may play a more significant role in trade documentation, and payment chains may become more complex and layered. Each additional layer reduces the visibility of cargo origin and ultimate transaction beneficiaries.
Exposure to sanctions-evasion networks
Connections to sanctions-evasion networks rarely arise from direct dealings with sanctioned actors. Instead, they emerge through intermediary trading companies, commodity brokers and maritime service providers that present as legitimate counterparties while facilitating transactions connected to shadow fleet vessels.
These connections can occur across a range of financial activities, including trade finance arrangements that support oil shipments, maritime insurance payments, vessel financing structures, and commodity trading transactions involving complex intermediary chains. In each case, the immediate counterparty may appear commercially legitimate while the underlying transaction ultimately benefits a sanctioned entity.
Enforcement actions have demonstrated how petroleum revenues linked to these networks can be routed through shell companies and offshore financial centres before entering the formal financial system. Layered corporate structures and fragmented payment pathways are used specifically to obscure beneficial ownership and complicate efforts to trace the source of funds.
The broader picture
Iran’s ability to maintain oil exports under extensive sanctions illustrates the adaptability of illicit economic networks operating within the global trading system. Sanctions rarely eliminate demand for commodities such as oil; instead, they incentivize the development of intermediary infrastructures capable of moving commodities through regulatory gaps. The recent temporary easing of US restrictions on certain Russian oil shipments, introduced to stabilize markets during the Iran crisis, adds a further dimension: by allowing some Russian crude to move through more direct or compliant channels, it increases the availability of competitively priced legal supply and reduces reliance on shadow-market blending arrangements, thereby altering the competitive dynamics and routing patterns that Iranian operators have relied on.
The geography of this network is not incidental. African maritime registries, including those in Cameroon, Comoros, São Tomé and Príncipe, and Tanzania, are embedded in the evasion architecture, providing flag registration to vessels operating with limited transparency and variable verification of ownership or operational history. These registries offer low-cost, accessible registration with comparatively lower compliance and oversight thresholds, making them attractive to operators seeking to obscure vessel identity. The region’s growing role in commodity trade and correspondent banking creates natural points of intersection with the transaction flows described above. These are not hypothetical or remote risks; they are the product of structural features that connect regional financial activity to global sanctions-evasion infrastructure. Exposure is therefore a question of probability rather than possibility.
Fuel trade capture in the Central African Republic
Fuel distribution in the Central African Republic (CAR) illustrates how commodity supply chains in fragile economies can be captured by politically connected intermediaries and structured to move value through pricing distortions, voucher monetization and documentation irregularities. The typologies identified, recognized features of trade-based money laundering, can enter the financial system through trade finance, correspondent banking and cross-border payments. For institutions with exposure to commodity trade in conflict-affected markets, the case presents live risk indicators rather than theoretical concerns.
Transactions linked to fuel trading in the CAR can introduce corruption risk, proceeds of crime and sanctions exposure into routine trade finance, correspondent banking and cross-border payment flows. A recent investigation by the Global Initiative Against Transnational Organized Crime (GI-TOC) shows how fuel supply chains have been used to generate revenue through opaque trading structures and irregular documentation, and how the proceeds can enter the formal financial system through apparently legitimate commercial transactions. The typologies identified represent live risk indicators rather than theoretical concerns.
The scale of the underlying problem
Illicit financial flows linked to trade manipulation remain a major concern across Africa. In 2015, the UN Economic Commission for Africa High-Level Panel on Illicit Financial Flows, chaired by Thabo Mbeki, estimated that the continent was losing more than US$50 billion annually through mechanisms such as trade misinvoicing and commodity manipulation. Although this figure is now over a decade old, more recent assessments suggest the structural vulnerabilities it identified have not diminished. Weak customs oversight and opaque trading structures persist in fragile and conflict-affected economies, including CAR.
Commodity supply chains and financial system exposure
Commodity supply chains in Central Africa intersect with regional banking channels through trade finance facilities, correspondent banking relationships and cross-border payment processing. Transactions linked to fuel imports, logistics providers and commodity traders can therefore pass through the financial system as part of ordinary commercial activity.
Where commodity markets involve politically connected intermediaries, opaque pricing structures or irregular trade documentation, these transactions may carry elevated financial crime risk. Payments linked to fuel distribution or regional supply chains may appear commercially legitimate while obscuring underlying value transfers.
Supervisory attention has also increased in recent years across the continent, particularly in relation to trade-based money laundering and complex cross-border financial flows. Financial institutions processing transactions linked to commodity trade in fragile or conflict-affected markets face growing expectations to identify pricing anomalies, documentation irregularities and sanctions exposure within supply chains.
How the scheme works
The GI-TOC investigation, based on trade data analysis, open-source intelligence and interviews conducted between late 2024 and mid-2025, identifies several mechanisms that illustrate how value can move through commodity supply chains.
One development has been the replacement of established fuel operators by intermediaries linked to political and security structures, including networks connected to Russian security actors operating in the country. The rapid emergence of new intermediaries in a strategic commodity sector is itself a red flag: it signals elevated politically exposed person risk and warrants enhanced know-your-customer and beneficial ownership checks before any related transactions are processed.
The investigation further describes the use of government fuel vouchers originally intended to supply state institutions and security services. In practice, these vouchers have also functioned as a mechanism for converting public resource allocations into privately tradable revenue. Traders receiving the vouchers can redeem the fuel and sell it commercially, allowing state resources to be monetized through private markets. When proceeds from these sales enter the banking system, the origin of the underlying value will not be visible through standard transaction documentation, making source-of-funds scrutiny essential for counterparties operating in this sector.
Pricing irregularities were another feature identified by investigators. Transaction prices within the CAR fuel market were often inconsistent with transparent market pricing structures. In trade-based money laundering typologies, pricing distortions allow value to be transferred across borders through over- or under-invoicing while transactions appear commercially legitimate. For trade finance teams, this reinforces the importance of verifying whether declared goods, quantities and prices are consistent with the characteristics of the trade route and counterparties involved.
Documentation issues also appeared along the CAR–Cameroon trade corridor, where investigators found evidence of inaccurate commodity classifications and customs declaration irregularities. Misclassification can reduce duties, obscure the nature of shipments and distort invoice values used in cross-border payments, all of which can affect the accuracy of the transaction picture available to correspondent banks and payments processors.
Sanctions exposure and the shadow fleet
Sanctions exposure adds another dimension to the risk environment. The same GI-TOC investigation found that in early 2025, approximately 30 000 tonnes of diesel linked to Russia’s shadow fleet were delivered to the region. The shipment was presented as humanitarian assistance despite documented links to Russian supply networks.
This example illustrates how commercial energy flows can be structured as bilateral assistance or humanitarian supply in ways that obscure sanctions exposure. Documentation may appear compliant while concealing vessel history, ownership structures or links to sanctioned entities. Standard SWIFT screening alone may not catch this exposure: beneficial ownership of the vessel operator and cargo origin documentation matter here. Transactions involving fuel shipments into CAR or neighbouring markets, therefore, warrant enhanced screening for indicators associated with shadow fleet activity, including vessel ownership changes, flag history and ship-to-ship transfers.
The CAR fuel trade illustrates how commodity allocation systems in fragile states can generate revenue for politically connected networks while appearing as ordinary commercial activity. The typologies identified in this case, voucher monetization, pricing manipulation, customs misclassification and sanctions evasion linked to shadow fleet activity, demonstrate how commodity supply chains in fragile markets can introduce corruption risk, proceeds of crime and sanctions exposure into otherwise routine financial transactions.
These are live risk indicators, not theoretical concerns. The channels through which this activity moves, trade finance, correspondent banking and cross-border payments, are the same ones that carry legitimate commercial activity. For institutions with exposure to commodity trade in fragile or conflict-affected markets, that makes pattern recognition, counterparty scrutiny and robust beneficial ownership verification essential tools for managing the underlying risk.
MARKET TYPOLOGY
THE CANADIAN FENTANYL ECONOMY
The GI-TOC’s Organized Crime Index 2025 identified synthetic drugs as the most widespread criminal market globally. It is present in 186 out of 193 assessed countries and is expanding faster than almost any other illicit trade. Unlike plant-based drugs, synthetic substances can be produced anywhere using commercially available equipment, and the market utilizes a vast, largely licit global chemical supply chain that is difficult to monitor. These structural advantages have lowered barriers to entry and accelerated the expansion of a geographically dispersed and financially lucrative economy that is growing more rapidly than many states’ institutional capacity to respond.
This challenge is not confined to wealthy, high-consumption markets in the Global North.
Africa, in particular, illustrates the scale and urgency of the problem, with synthetic stimulant markets long established in the southern region. For decades, for instance, South Africa has contended with a severe crisis involving methamphetamine, locally known as ‘tik’. The epidemic remains among the most entrenched on the continent. There are also early indications of fentanyl emerging within the local drug supply.
In West Africa, the picture is evolving rapidly.
The synthetic cannabinoid compound ‘kush’, which is made from imported active ingredients blended locally, has caused significant harm in Sierra Leone and is spreading across the Mano River basin. More recently, there have been early indications of the presence of nitazene in parts of Africa, connecting the region to the same class of ultra-potent synthetic opioids now driving overdose mortality in Europe. These developments confirm that the challenge posed by synthetic drugs is genuinely global, most acutely affecting regions where public health and law enforcement systems are constrained.
Against this global backdrop, the Canadian case study is both instructive and relevant.
Drawing on the GI-TOC’s 2025 trilateral study of the North American fentanyl market, the Canadian case illustrates the financial architecture of the trade and the transaction patterns most relevant to financial institutions. Fentanyl is synthesized from industrial chemicals and moves through a supply chain spanning various jurisdictions. Precursors ship from China, Germany, India and Guatemala into Mexico, where fentanyl is synthesized and trafficked north, often pressed into counterfeit pills before reaching consumers. Approximately US$1.4 million in licit trade crosses the US–Mexico border every minute, an enormous flow of goods that illicit supply chains exploit for cover. What began as a crisis of over-prescription has evolved into a highly adaptive criminal market dominated by illicitly manufactured fentanyl of unpredictable potency.




Key statistics
|
UNITED STATES |
CANADA |
MEXICO |
|
|---|---|---|---|
|
Deaths |
1.1m+ overdose deaths since 2000; 25 per 100k/year |
50 000+ opioid deaths since 2016; 21/day |
Homicide: 24 per 100k/year; fentanyl revenues fund cartel violence |
|
Economic cost |
US$1.5 trillion/year |
CAD8.8 billion/year lost productivity |
Embedded in civil instability |
|
Scale of use |
Nearly 25m Americans used illicit fentanyl in past year |
Males 30–39 most at risk |
Growing domestic consumption |
The independent domestic market
Canada’s fentanyl market operates differently to the US–Mexico model. Production is now largely domestic, with precursors sourced from China and production techniques learned from Mexican criminal organizations. The Canadian market is therefore becoming increasingly self-sufficient, with trade typically moving west to east across Canada rather than south across the US border. The fentanyl economy does not rely on a parallel financial system. It operates through ordinary financial infrastructure, business accounts, wire transfers, trade finance, real estate transactions and cryptocurrency exchanges. Financial institutions are therefore not merely observers; they form part of the infrastructure through which illicit proceeds move.
For financial institutions, the clearest detection opportunities arise at the procurement stage, where chemical purchases must pass through the banking system. Unusual wire transfers to chemical suppliers in China, India or Germany, particularly from businesses registered as health supplement manufacturers, pharmaceutical testing laboratories or cleaning product companies, warrant scrutiny when the declared business activity does not plausibly explain the volume or type of chemicals being ordered.
Payments routed through intermediary jurisdictions such as Singapore, Hong Kong or South Korea, with no evident commercial rationale, may represent layering activity intended to obscure the beneficiary. Structuring patterns are also observed, including repeated low-value transfers under CAD1 000 to the same chemical supplier, which are inconsistent with the scale of the purchasing entity.
Cryptocurrency activity can provide another signal, particularly when crypto purchases are followed swiftly by payments to chemical vendors or addresses associated with darknet marketplaces. Import–export companies purchasing dual-use chemicals in volumes inconsistent with their declared client base should similarly be treated as elevated-risk relationships.
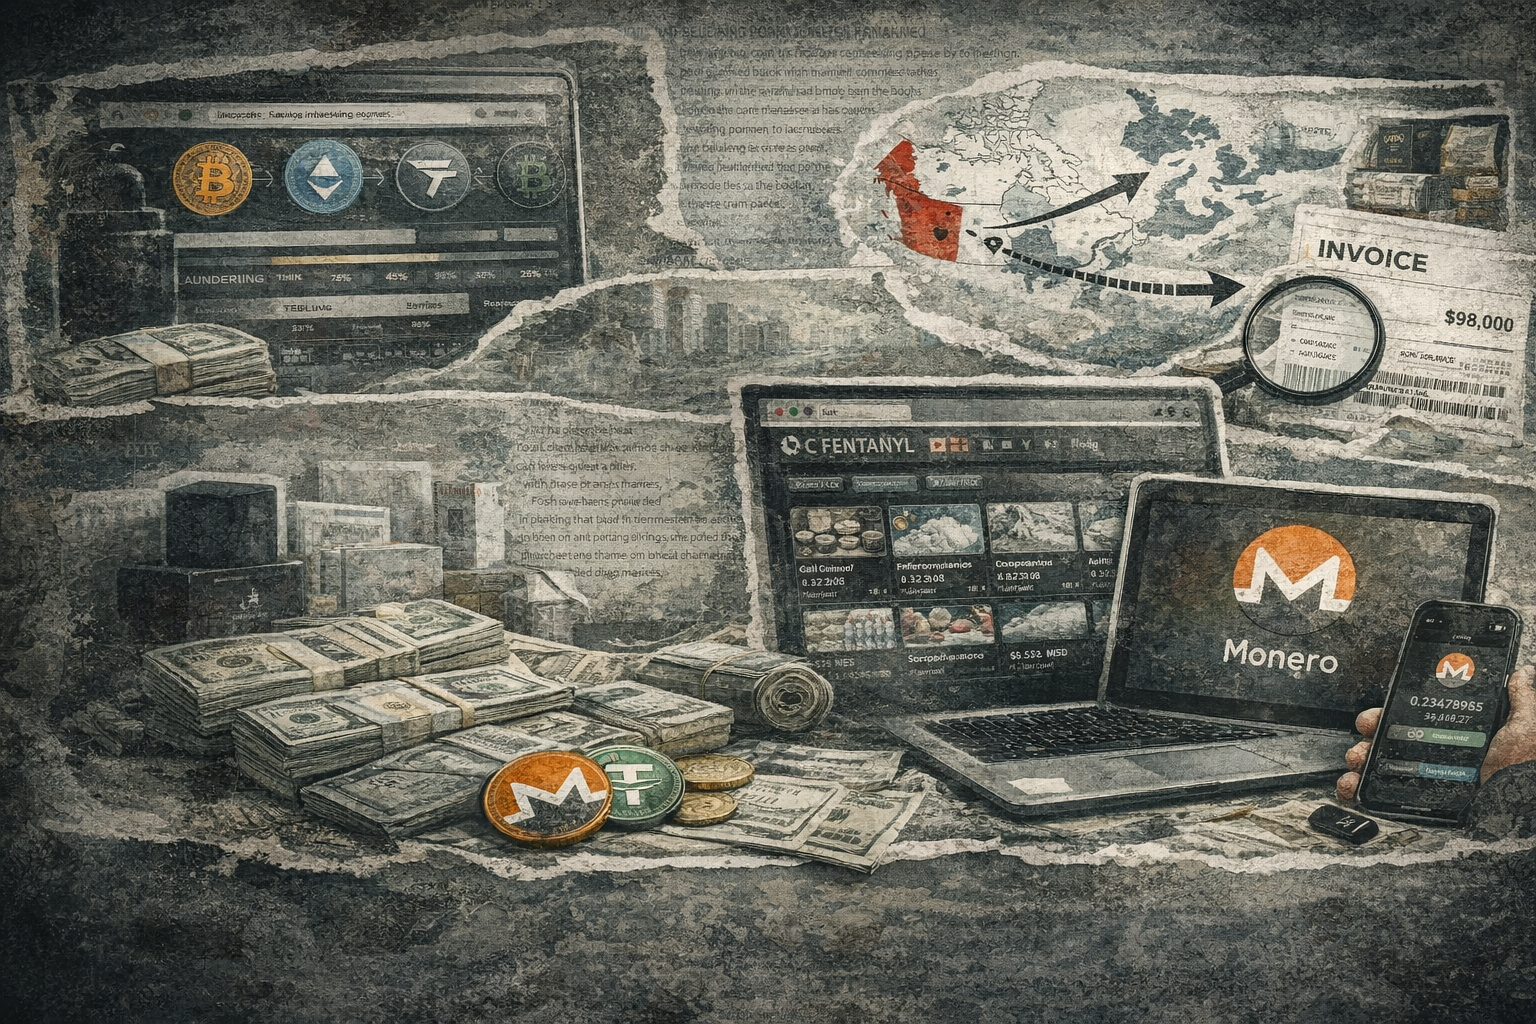
The five-stage supply chain and its financial traces

1. Procurement
Criminal operators purchase fentanyl precursors from suppliers in China, India, Germany and Guatemala, typically through front companies registered as supplement manufacturers, pharmaceutical testing labs or cleaning product businesses. Payments are routed through intermediary jurisdictions such as Singapore, Hong Kong and South Korea, often with no obvious commercial rationale for the layering. Roughly 90% of identified Chinese precursor suppliers accept cryptocurrency, primarily Bitcoin or Tether. Shipments are physically disguised in mislabelled food containers or industrial goods consignments.
These procurement methods can create indicators of financial crime risk within banking systems. Examples include wire transfers from businesses operating in chemical-adjacent sectors to suppliers in Asia or Europe that are inconsistent with the customer’s stated business activity; payments routed through intermediary jurisdictions; repeated low-value transfers below CAD1 000 suggestive of structuring; purchases of cryptocurrency followed by payments to chemical vendors; and payments to freight forwarders where cargo documentation or manifests do not align with the declared goods.
2. Production
Canada’s domestic labs operate primarily in British Columbia, Alberta and Ontario, typically in rural rental properties. Investigations indicate that some operators use legitimate business fronts, such as supplement or cleaning companies, to explain chemical purchases and subsequent cash deposits. The Gupta synthesis method, a simplified chemical process requiring fewer steps and basic laboratory equipment, makes it easier for illicit laboratories to manufacture drugs on a large scale.
These production activities can generate financial red flags. Indicators may include chemical purchases inconsistent with declared business activity; payments to laboratory equipment suppliers by entities with no research or manufacturing profile; cash deposits from supplement or cleaning businesses disproportionate to their declared scale; and rental payments for remote industrial or rural properties.
3. Wholesale
Distribution flows overwhelmingly from west to east, with production centred in British Columbia and Alberta and consumption concentrated in Ontario, Quebec, and the Atlantic provinces. Wholesale settlement payments between producers and distributors range from tens to hundreds of thousands of dollars, typically made in bulk cash (transported by money couriers), by false invoicing through front companies, or in cryptocurrency for darknet-arranged transactions. The report suggests that domestic distribution can be more economically attractive than southbound export.
4. Retail and dark web
At street level, the market operates through layered distribution tiers: organized crime groups hold supply and set wholesale prices; local distributors resell to street dealers; transactions with end users are typically completed in small-denomination cash, often in under a minute. Canada’s dominant domestic platform, WeTheNorth (WTN), hosts over 4 800 drug listings on a domestic-only shipping model; carfentanil, an ultra-potent synthetic opioid, remained available as recently as October 2025, despite an official ban. Key financial signals are cryptocurrency payments for purchases and courier or postal payments for delivery logistics.
5. The laundering layer
Investigations suggest that Chinese-linked money laundering networks may be involved. In documented cases, brokers have used Mexican and Chinese bank branches to handle bulk cash proceeds, routing funds to front companies through interbank transfers. Trade-based money laundering uses misinvoiced import/export transactions of everyday goods, such as electronics and vaping devices, to transfer value across borders. Real estate and luxury goods are purchased through nominees (family members, romantic partners) to convert cash into assets while concealing beneficial ownership.
Cryptocurrency mixers and tumblers are used to obscure blockchain trails. Privacy coins, such as Monero, and stablecoins, such as Tether (USDT), are increasingly preferred for their resistance to blockchain analysis. The US Office of Foreign Assets Control has also sanctioned Bitcoin, Ethereum and Tron addresses linked to fentanyl transactions. Online gambling platforms serve as an integration channel, with proceeds deposited as wagers and withdrawn as apparent winnings.
The financial patterns documented in the Canadian fentanyl market are not unique to that context. The same structural features recur across synthetic drug markets globally: front companies in chemical-adjacent sectors, layered payment routes through intermediary jurisdictions, nominee real estate purchases, and cryptocurrency used to bridge procurement and retail. Financial institutions operating in markets with significant synthetic drug activity will not encounter transactions labelled as drug-related. Instead, they will see a supplement company wiring money to Guangzhou, a freight broker whose invoices do not match the declared goods, or a real estate purchase by an individual with no verifiable income. Recognizing these patterns is not only good practice in terms of compliance; it also helps address a global public health challenge. According to the UN Office on Drugs and Crime, synthetic drugs now affect more countries than any other illicit substance and are a key driver of the global drug problem.
Best practice responses to synthetic drug financial crime
While most jurisdictions criminalize money laundering, a critical gap persists. Prosecutors must still demonstrate that funds are derived from criminal activity and that the accused was aware of this or acted recklessly. In practice, this evidentiary burden makes it difficult to prosecute professional money laundering networks that are deliberately kept distant from underlying criminal activity.
Enable standalone money laundering offences:
In many jurisdictions, prosecutors must establish that funds are derived from criminal activity to secure a money laundering conviction. Enabling standalone offences would allow authorities to target professional laundering networks without first needing to prove the underlying predicate offence.
Introduce targeted administrative listings mechanisms:
While not all facilitators or intermediaries in the synthetic drug supply chain meet the criminal evidence threshold for prosecution, they may still pose a significant financial risk. Administrative listing regimes can restrict access to banking and payment systems without the need for a conviction.
Strengthen beneficial ownership transparency:
A significant proportion of illicit funds are laundered through real estate, corporate vehicles, and other assets held through nominees or opaque structures.
Strengthen the conversion of financial intelligence into enforcement action:
Financial intelligence units generate substantial data, but disclosures do not consistently translate into investigations. Structured feedback loops between financial intelligence units and law enforcement agencies are essential to ensure intelligence leads to operational outcomes.
Ensure sustained resourcing for financial crime investigations:
Financial crime investigations are often under-resourced relative to their complexity. Sustained and dedicated resourcing is required to support long-term, cross-border investigations.
Strengthen public–private collaboration across the financial system:
Illicit financial flows linked to synthetic drugs are increasingly dependent on both traditional and digital financial infrastructure, including cryptocurrencies. Enhanced public–private partnerships, involving information sharing between financial institutions, virtual asset service providers and analytics firms, could help to improve detection and disruption across the financial system.
Resources & events

Project CRAAFT – Virtual Threats: Terrorist Financing via Online Gaming
2025
Examines how extremist actors exploit online gaming platforms for propaganda, recruitment and potential fundraising.
ComplyAdvantage – The State of Financial Crime
2026
Highlights key financial crime trends, including AI-enabled fraud, real-time payment risks and growing regulatory pressure.
ICAIE – Spring Policy Brief
2026
Explores how transnational criminal networks exploit trade routes, governance gaps and financial systems to move illicit value.
FinCEN – Issues Beneficial Ownership Relief Order
2026
Details FinCEN's 2026 easing of beneficial ownership requirements, allowing reliance on existing data unless risk indicators emerge.
Deloitte – Tackling Fraud in a Borderless World
2026
Outlines Deloitte's latest thinking on what a genuinely global fraud architecture could look like, highlighting the need for coordination to match existing ambition
European Anti-Financial Crime Summit
29 April 2026
Dublin, Ireland
---
A high-level summit bringing together regulators, financial institutions and compliance leaders to discuss emerging financial crime risks, regulatory developments and enforcement trends across the banking sector.
Africa Fraud, Security & Compliance (AFSC) Summit
3–4 June 2026
Nairobi, Kenya
---
The Africa Fraud, Security & Compliance (AFSC) Summit brings together banking leaders, regulators, compliance professionals and fintech experts to address emerging fraud and financial crime risks in African financial systems. Discussions will focus on threats such as AI-enabled fraud, synthetic identities, trade-based money laundering, mobile money vulnerabilities and cross-border payments security. The event aims to share practical strategies for strengthening fraud prevention, cybersecurity resilience and compliance frameworks across the region’s rapidly digitizing financial sector.
About the Global Initiative GI-TOC
The Global Initiative Against Transnational Organized Crime is a global network with over 700 Network Experts around the world. The Global Initiative provides a platform to promote greater debate and innovative approaches as the building blocks to an inclusive global strategy against organized crime. www.globalinitiative.net
 Built with Shorthand